 |
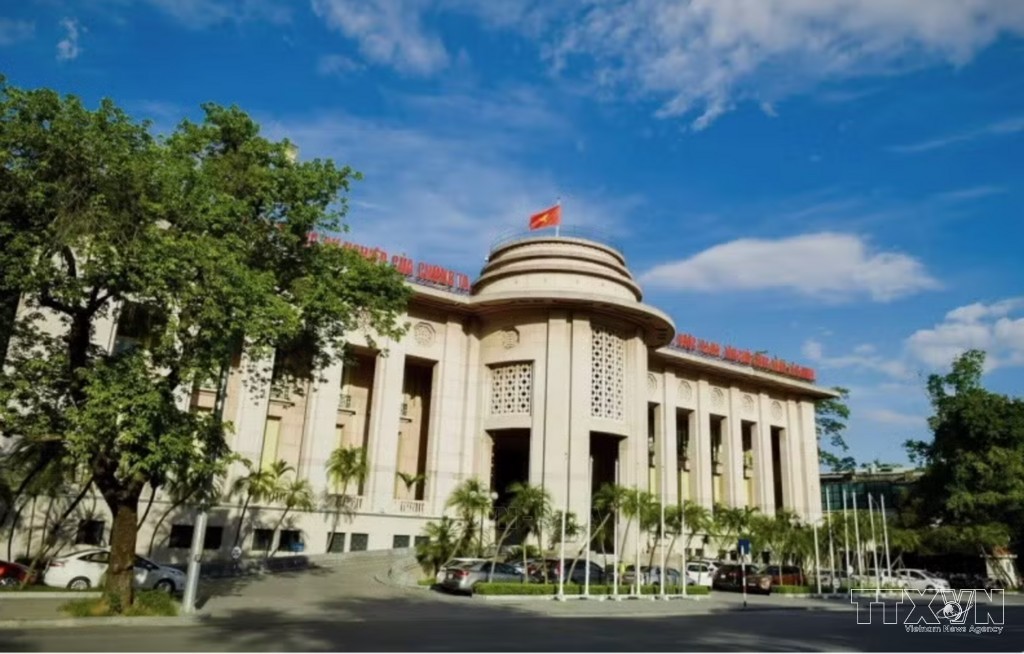
| The State Bank of Vietnam headquarters in Hanoi (Illustrative photo: VNA) |
Hanoi (VNA) – From November 1, 2026, the provision of borrowers’ credit information for voluntary organisations, foreign credit information organisations and other organisations must be based on the borrowers’ explicit and specific consent.
The requirement is included in Circular No. 46/2026/TT-NHNN recently issued by the State Bank of Vietnam (SBV), which amends and supplements a number of provisions of Circular No. 15/2023/TT-NHNN on credit information-related activities. The new circular will take effect on November 1, 2026.
Under the new regulations, borrowers’ credit information may be provided for voluntary organisations, foreign credit information organisations and other organisations in accordance with regulations.
However, such provision must have the borrower’s consent as required by relevant laws and comply with the information exchange agreement with the National Credit Information Centre of Vietnam (CIC).
Notably, the borrower’s consent must be given through a clear and specific method that can be printed or copied in writing, including in electronic form or another verifiable format.
The new provision is expected to establish a clearer framework for sharing borrowers’ credit information while requiring consent to be identifiable, retainable and verifiable throughout the information-sharing process.
Circular 46/2026 also revises regulations on the methods and frequency of providing credit information. Accordingly, credit information must generally be provided in electronic data form in accordance with the Credit Information Indicator System.
Where some or all groups of credit information indicators cannot be provided electronically, credit institutions and voluntary organisations may provide the information in writing as agreed with the CIC.
For credit institutions, the frequency of information provision must comply with the Credit Information Indicator System issued under a decision of the SBV Governor. For voluntary organisations, the frequency is determined by their information exchange agreements with the CIC.
The circular also clarifies requirements concerning annual financial statements of corporate borrowers. Such statements must have been submitted to tax authorities or audited. For foreign corporate borrowers, annual financial statements must comply with international accounting standards or the accounting standards of the country where they are headquartered.
Circular 46/2026 also adds and revises provisions concerning member banks and related persons of borrowers in line with relevant regulations on the Vietnam International Financial Centre and credit institutions./.